 Bridge
Offline payments · for banks and agent networks
Payments that keep working when the network doesn't.
Load online. Pay offline. Settle when the signal returns.
How it works
| Step | Network | What happens |
|---|---|---|
| Load | Online | Value moves from the customer's account to a device ledger account |
| Pay | Offline | Devices exchange a signed payment |
| Settle | Online | The batch posts; duplicates are rejected |
| Credited | Online | The payee is credited |
Where the money is
The money never leaves the bank.
Value on a device is held in a device ledger account at the bank. Nothing is created offline, so the bank never carries money that isn't there.
Customer account
at the bank
Device account
at the bank · spendable offline
Payee account
at the bank
Where it works
Wherever the signal gives up.
Agents
Cash-in and cash-out where the agent's connection is weak.
Markets and farm gates
Trade where there's no mast nearby.
Transport
Bus, keke and ferry fares, in motion.
Crowded venues
Thousands of phones, one mast.
Outage fallback
Keep taking payments when the network or a switch is down.
Merchants without a POS
A phone is enough to get paid.
Routes to market
Three ways to switch it on.
Next
Mobile SDK
Offline payments inside your Android and iPhone apps.
Next
POS SDK
Offline acceptance on Android POS terminals.
Controls
Your risk rules, on every device.
- Limits on each device by KYC tier, set by you
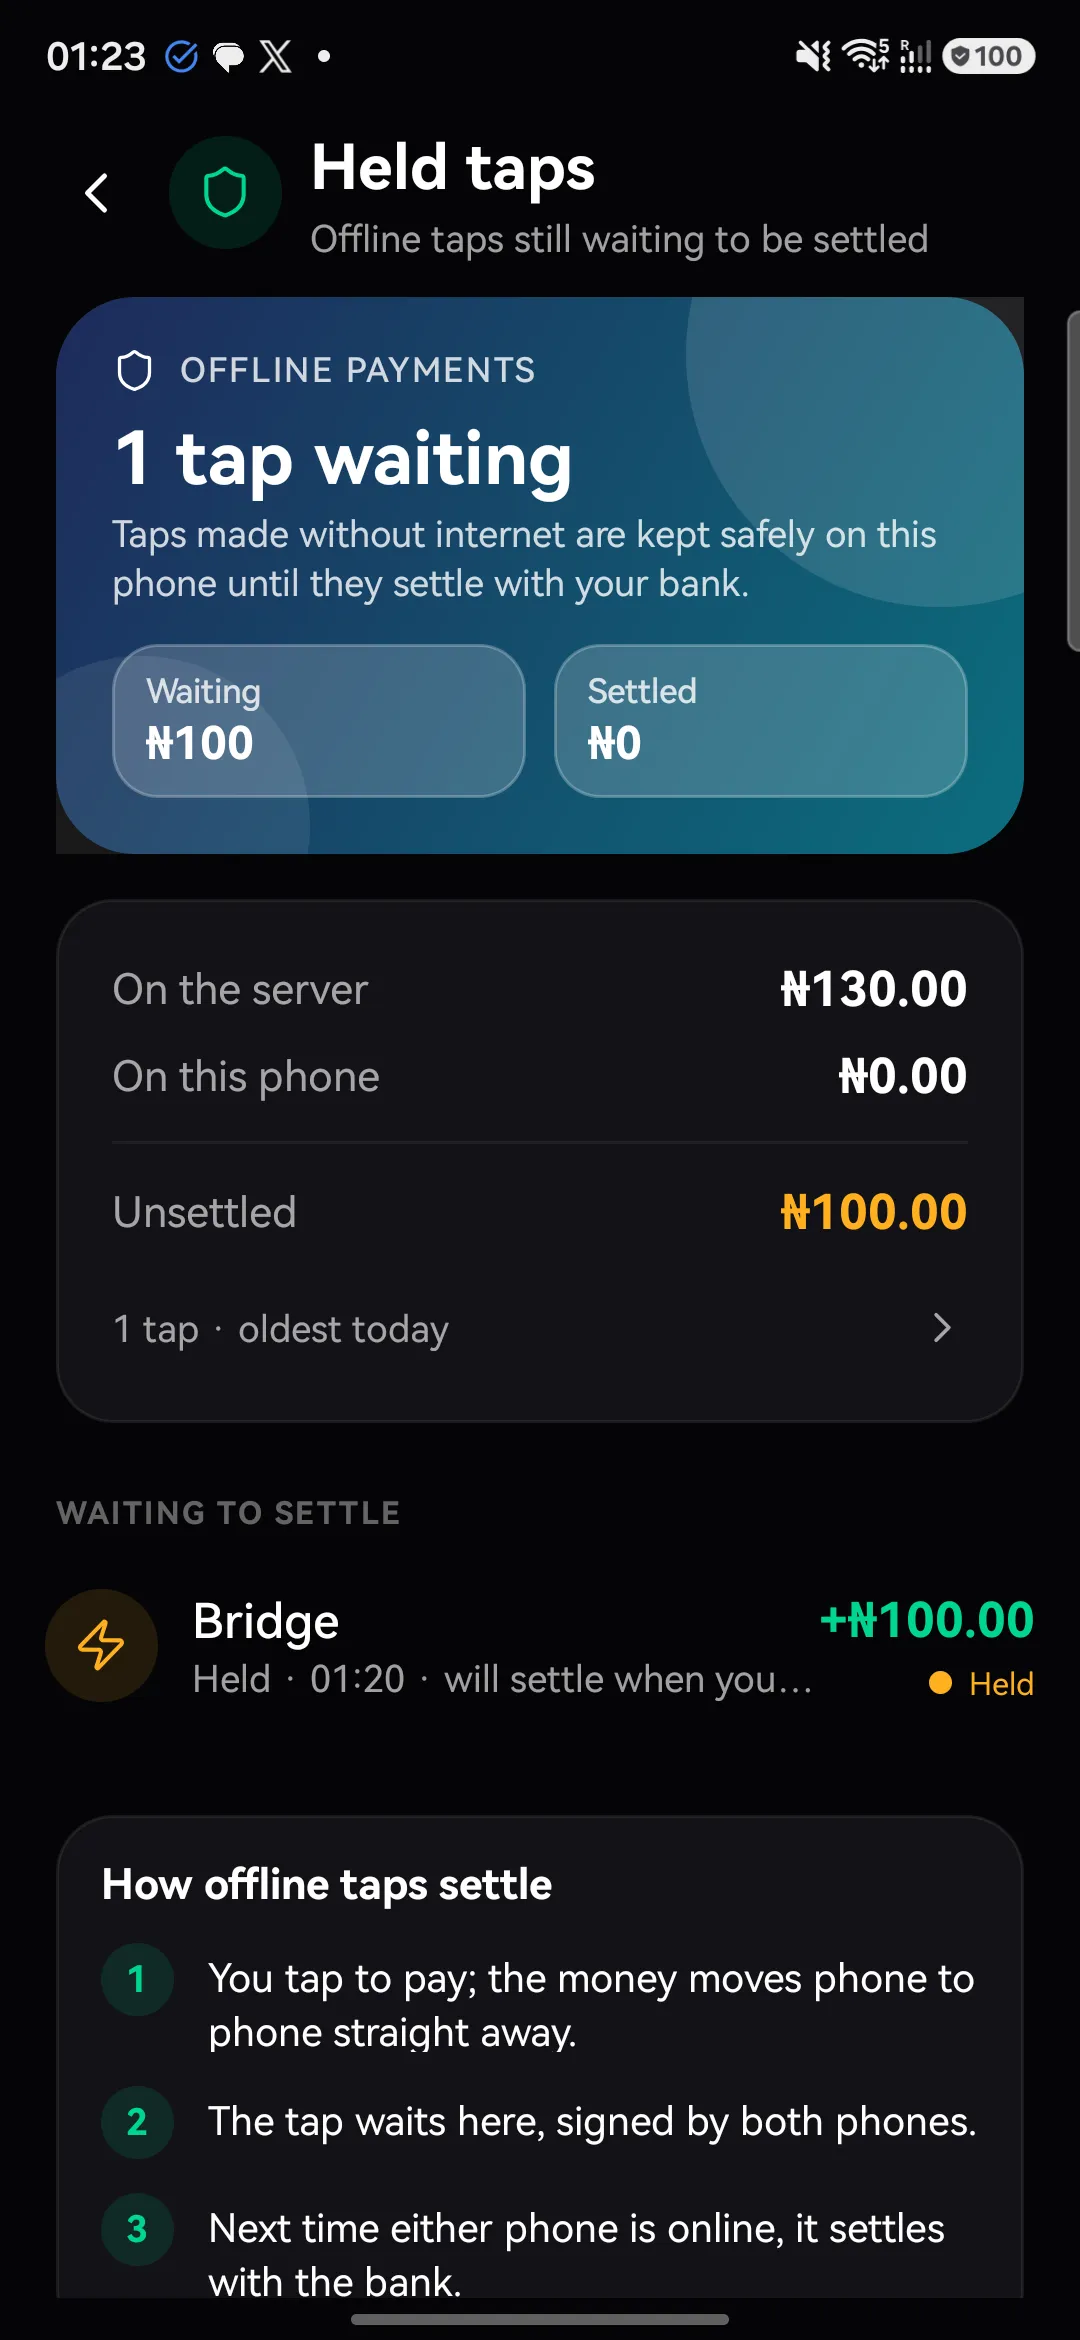
- Replay protection: a payment can settle once
- A device's cap grows from its settled history
- Freeze a device from any channel
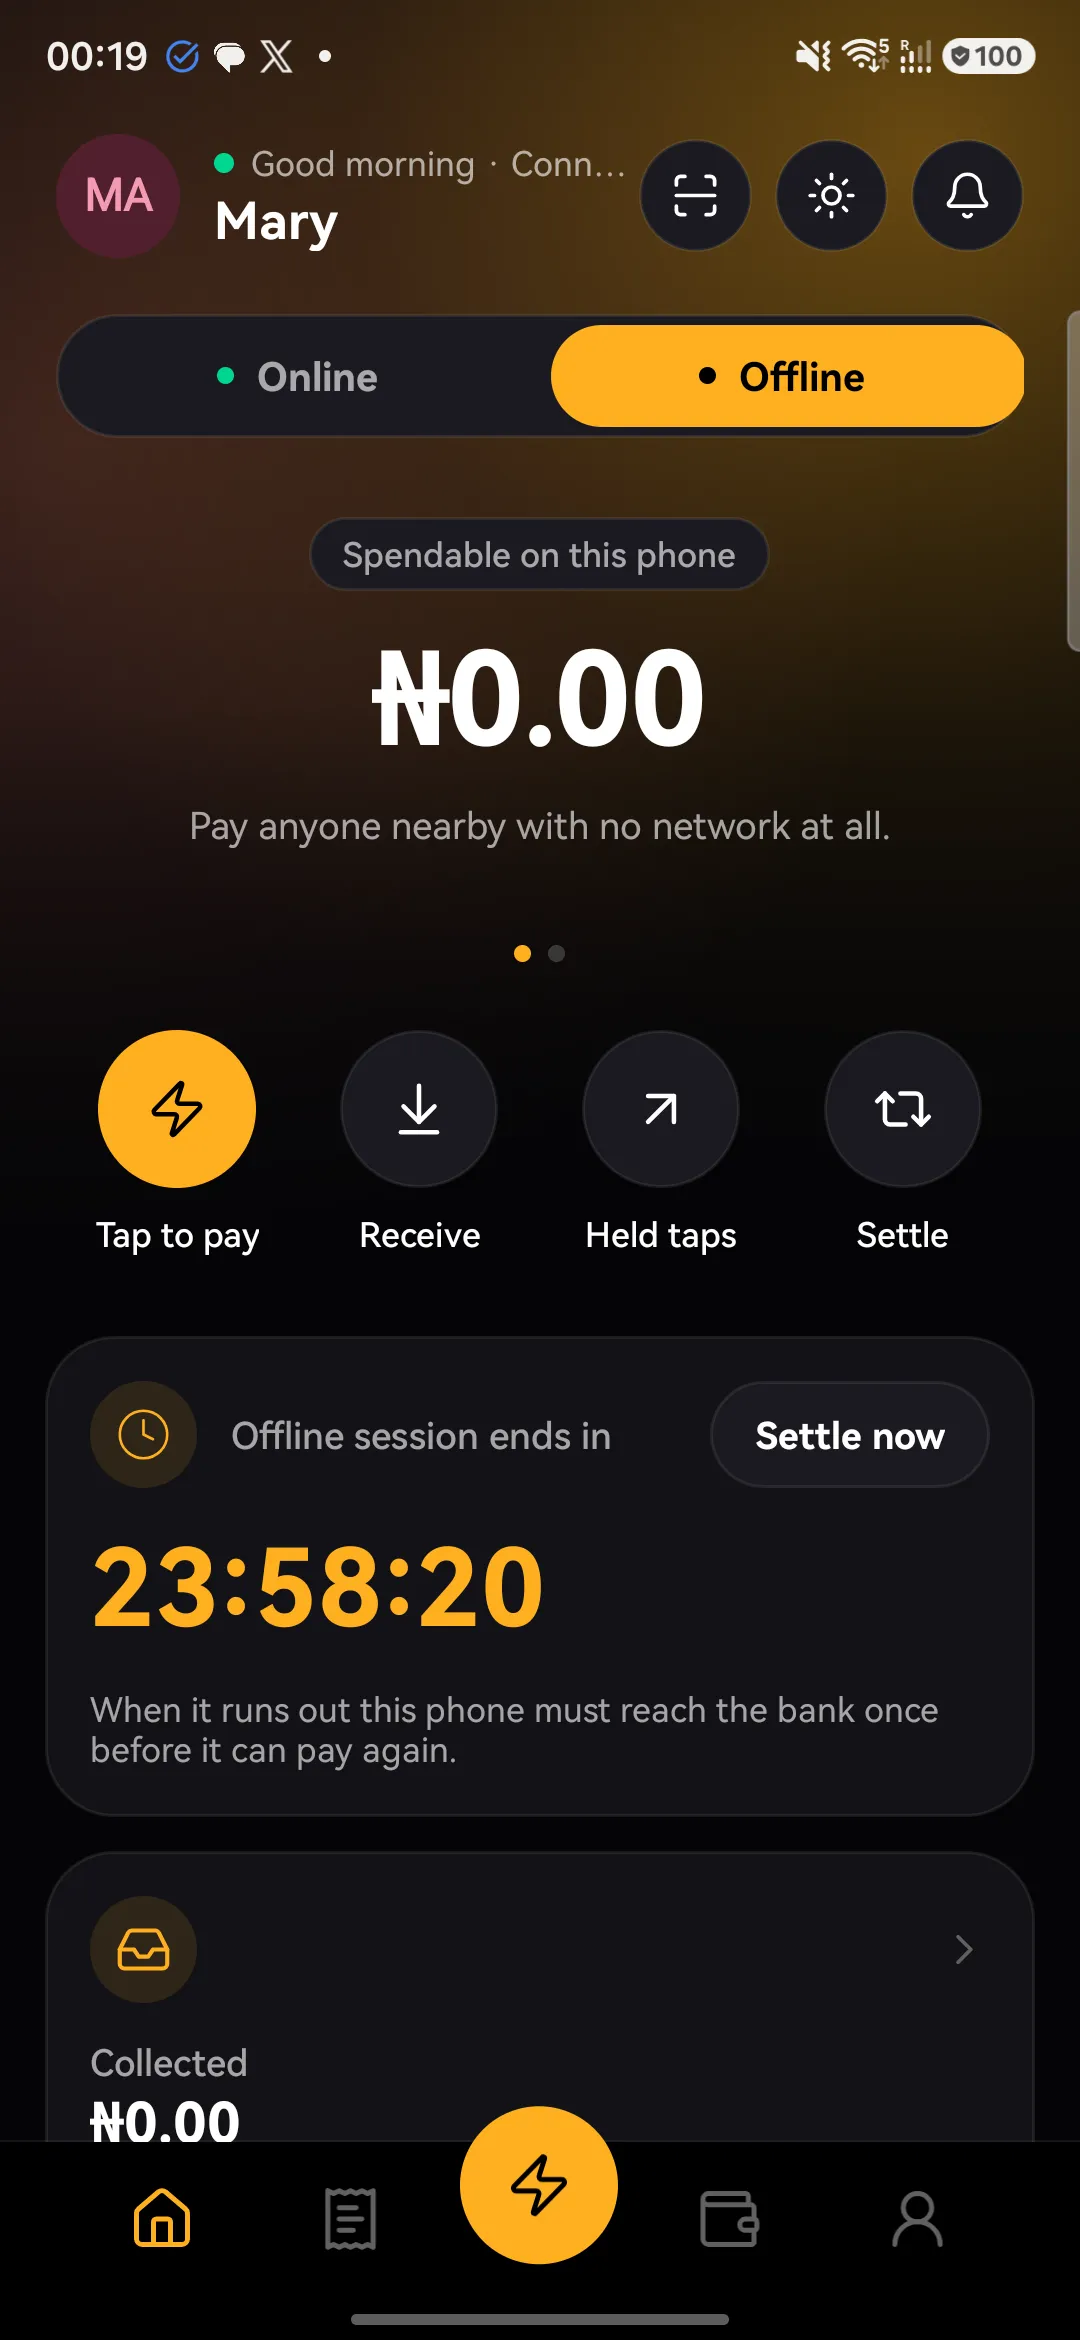
- An offline session expires, so a device must reach you before it can pay again
Reference build
See it in the Bridgemoni app.
Our own customer app uses the same offline endpoints, phone to phone.
Pilot
Start with a pilot.
One channel, one region, your limits.
Bridge for Business
Tell us what you're building.
We'll come back with what's live for you today, and what's next.